Safety Pays: How ADAS Technology Is Rewriting the Math on Insurance Premiums and Road Risk
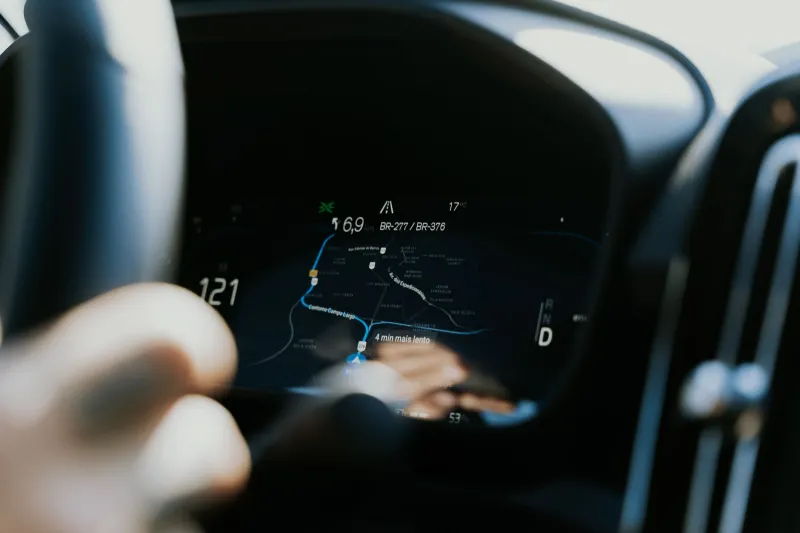
For decades, the calculus of auto insurance was relatively straightforward: your age, your driving history, your ZIP code, and the make and model of your vehicle determined what you paid each month. The assumption embedded in that formula was simple — the car itself was largely passive. The driver was the variable.
That assumption is eroding fast.
Advanced driver assistance systems — collectively known as ADAS — have moved from optional extras to standard equipment on a growing share of new vehicles sold in the United States. Automatic emergency braking, lane-keeping assist, blind-spot monitoring, and adaptive cruise control are no longer selling points exclusive to luxury trim levels. They are increasingly the baseline. And as penetration deepens across the market, insurers, safety researchers, and automakers are beginning to grapple with a question that carries enormous financial and societal weight: are these systems actually making driving safer, and if so, who benefits?
The early evidence suggests the answer to the first part is yes — with important caveats.
What the Crash Data Is Revealing
The Insurance Institute for Highway Safety (IIHS) has been among the most rigorous trackers of ADAS effectiveness in real-world conditions. Its research into automatic emergency braking (AEB) found that vehicles equipped with the technology were involved in rear-end crashes at rates roughly 50 percent lower than comparable vehicles without it. Lane departure warning systems, according to separate IIHS analysis, have been associated with meaningful reductions in single-vehicle, sideswipe, and head-on crashes — the categories most likely to result in fatalities.
The National Highway Traffic Safety Administration (NHTSA) has similarly documented declining injury rates in segments where ADAS adoption is highest. While overall US traffic fatalities remain stubbornly elevated compared to peer nations — a complex problem rooted in road design, speed limits, and driving culture — the trajectory in specific crash categories is moving in a favorable direction.
Not every system delivers equal results, however. Research consistently shows that AEB and forward collision warning produce the most statistically significant reductions in real-world incidents. Lane-keeping assist and blind-spot monitoring show positive trends but with more variability across studies, partly because their effectiveness depends heavily on how they are implemented and how drivers interact with them over time.
How Insurers Are Responding — Slowly
Given the data, one might expect insurers to have already built robust ADAS discounts into their pricing models. The reality is more complicated.
Several major carriers, including Allstate, Progressive, and Liberty Mutual, have introduced premium discounts for vehicles equipped with specific ADAS features. The discounts vary widely — typically ranging from two to ten percent depending on the system and the insurer — and the criteria for qualification are not always transparent to consumers. Industry observers note that insurers are still accumulating the actuarial data necessary to price ADAS risk with precision, particularly as the technology itself continues to evolve.
There is also a counterintuitive wrinkle in the economics. Vehicles equipped with ADAS sensors, cameras, and radar arrays are significantly more expensive to repair after a collision. A bumper replacement that once cost a few hundred dollars can now run into the thousands when it requires recalibration of forward-facing cameras or radar modules. This repair cost inflation has partially offset the claims frequency reductions that ADAS would otherwise deliver to insurers' bottom lines — and in some cases has pushed comprehensive premiums upward even as accident rates fall.
The net effect for consumers is mixed. Drivers in newer, well-equipped vehicles may see modest premium reductions tied to safety features, but they are simultaneously absorbing higher repair costs when incidents do occur. The full financial benefit of ADAS, from an insurance perspective, remains a work in progress.
The Liability Question Grows More Complex
As ADAS systems become more capable and more prevalent, questions of driver liability are becoming considerably more nuanced. When a vehicle equipped with lane-keeping assist drifts into another lane and causes an accident, who bears responsibility — the driver who relied on the system, or the manufacturer whose software failed to intervene effectively?
US courts and regulators have not yet established clear, uniform standards for adjudicating these scenarios. NHTSA has been gradually developing frameworks for automated system accountability, but the legislative landscape remains fragmented across states. Plaintiffs' attorneys and insurance defense firms are both investing heavily in understanding how ADAS event data recorders — the automotive equivalent of a flight data recorder — can be used to reconstruct incidents and assign fault.
Automakers, for their part, have been careful in how they market these systems. Ford, General Motors, Toyota, and others consistently emphasize that ADAS features are driver assistance tools, not autonomous replacements for human attention. The marketing language matters legally: it establishes an expectation that the driver remains responsible, even when the vehicle is actively intervening in the driving task.
Redesigning the Vehicle Around Safety Economics
The downstream implications for vehicle design are significant. As insurers develop more sophisticated ADAS pricing models, manufacturers will face growing pressure to equip even entry-level vehicles with the systems that demonstrably reduce claims frequency. NHTSA has already moved toward making AEB a federal requirement on new passenger vehicles — a regulatory shift that will accelerate standardization across the industry.
This convergence of regulatory pressure, insurance incentives, and consumer demand is reshaping product planning cycles. Automakers are increasingly treating ADAS not merely as a safety feature but as a financial instrument — one that can influence total cost of ownership calculations and, by extension, purchasing decisions. A vehicle with a strong IIHS safety rating and a comprehensive ADAS suite may command a lower insurance premium over its ownership life, effectively subsidizing a portion of its higher sticker price.
For fleet operators and commercial buyers, the math is already being calculated explicitly. Corporate fleet managers at large organizations routinely factor projected insurance savings from ADAS-equipped vehicles into procurement decisions, and the numbers increasingly favor the more capable systems.
The Road Ahead
The relationship between advanced driver assistance technology, insurance pricing, and accident outcomes is still being written. The data directionally supports optimism — fewer rear-end collisions, reduced lane-departure incidents, and growing insurer recognition that these systems reduce risk. But the story is not without friction. Repair cost inflation, inconsistent system performance across manufacturers, and unresolved liability questions mean that the full economic and societal dividend of ADAS has not yet been collected.
What is clear is that the passive vehicle is becoming a relic. As cameras, radar, and software assume a more active role in the driving experience, the industry's foundational assumptions about risk, responsibility, and cost will continue to shift. For consumers navigating a new-vehicle purchase today, understanding what their ADAS suite actually does — and what it costs to repair — is no longer optional knowledge. It is essential arithmetic.